Archived Insight | March 30, 2021
On March 26, 2021, the IRS announced that the cost of certain personal protective equipment (PPE) to prevent the spread of COVID-19 bought since January 1, 2020 is a medical expense under the tax code and may be covered or reimbursed by health plans, including account-based plans.
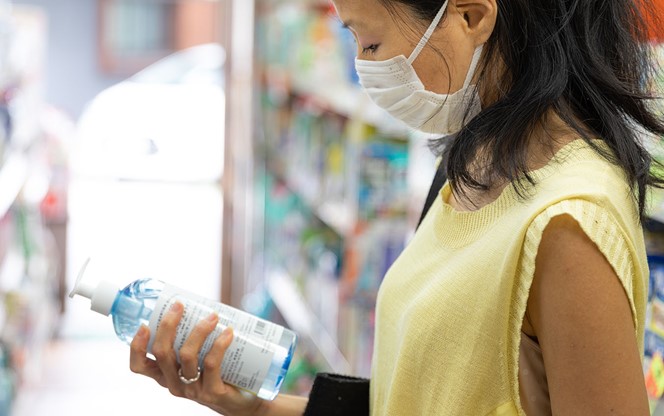
Eligible PPE incudes masks, hand sanitizer and sanitizing wipes purchased for the primary purpose of preventing the spread of COVID-19.
IRS Announcement 2021-7 clarifies that health plan sponsors can choose to cover COVID-19-related PPE and permit reimbursement of expenses for such equipment from account-based plans such as:
As a medical expense under the tax code, individuals may also seek reimbursement for COVID-19-related PPE from health savings accounts.
Sponsors of group health plans that wish to cover COVID-19-related PPE or permit reimbursement from health FSAs or HRAs may amend their plan documents to cover or reimburse expenses incurred since January 1, 2020.
The amendment deadline is the last day of the first calendar year beginning after the end of the plan year in which the amendment is effective. For example, a calendar-year plan that will cover PPE as far back as January 1, 2020 would need to be amended by December 31, 2021. A retroactive amendment cannot be adopted after December 31, 2022.
Plan sponsors should determine what types of COVID-19-related PPE their health plans, FSAs and HRAs will cover and amend plans accordingly. Plan sponsors that do not amend the plan documents right away will need to operate their plan consistent with the intended amendment.
In addition, plan sponsors should prepare to answer questions from participants about those expenses.

This page is for informational purposes only and does not constitute legal, tax or investment advice. You are encouraged to discuss the issues raised here with your legal, tax and other advisors before determining how the issues apply to your specific situations.